Rates are hovering near 7%, and if you've been watching them the way a lot of buyers do right now, you already know the frustration. They move up a little, then down a little, and nobody seems to agree on what comes next. What I tell buyers I work with here in the Wilmington area is this: stop trying to time the market and start building a budget that holds up no matter what rates do.
That's what rate-proofing really means. It's not about finding a magic number or waiting for the perfect moment. It's about knowing your real numbers before you fall in love with a house.
Key Takeaways
Start with a payment, not a price. Decide what monthly amount feels comfortable before you set a price ceiling.
Test three scenarios. Run your numbers at a lower rate, today's rate, and a rate about 0.50% higher so you can see the full range.
Rate swings matter more than people expect. On a $405,000 loan, the difference between 6.50% and 7.50% is roughly $272 per month.
Your real payment includes a lot more than principal and interest. Property taxes, insurance, flood coverage, HOA dues, and maintenance all belong in the number.
Coastal properties carry costs that inland buyers often don't expect. Flood zones, separate wind policies, and HOA amenity fees are common here and can add hundreds of dollars monthly.
Preapprovals have a shelf life. If rates shift or your finances change, update yours before making offers.
Waiting can be the right call, but only for the right reasons. If the stress-tested payment already feels tight, that's a signal worth respecting.
How Much Can a Mortgage Rate Change Your Payment?
More than most buyers realize until they actually see the numbers side by side. Freddie Mac reported a 7.03% average on a 30-year fixed mortgage as of late September 2026, but your actual quote will depend on your credit, your down payment, your loan type, and whether you're buying a primary home or a second home.
Here's a simple example. Take a $450,000 purchase with 10% down, leaving a $405,000 loan. Here's what principal and interest alone looks like across three rate scenarios:
Scenario | Rate | Monthly P&I |
|---|---|---|
Lower | 6.50% | $2,560 |
Current benchmark | 7.03% | $2,703 |
Higher | 7.50% | $2,832 |
That's a $272 spread from the low end to the high end, before a single dollar of taxes, insurance, or HOA dues.
Compare a Lower-Rate Payment
If rates drop before you close, that's genuinely good news. But treat it as upside, not as the thing that makes the purchase work. If a home only pencils out at 6.50% and you're being quoted 7.00% today, that gap is real and worth addressing before you go under contract.
Calculate the Expected-Rate Payment
Ask your lender for an actual Loan Estimate, not just a ballpark from an online calculator. A Loan Estimate shows your rate, APR, any points you're paying, mortgage insurance if it applies, and your estimated cash to close. That's the document that tells you what the loan actually costs, not just what shows up in your monthly payment.
Test a Higher-Rate Payment
Add about 0.50 percentage points to the rate you're being quoted today and recalculate. If that higher payment still leaves room for savings, normal life expenses, and a little breathing room, you're probably in the right price range. If it feels tight, that's worth knowing now rather than two weeks before closing.
What Belongs in a Wilmington Home Budget?
Principal and interest is the number most buyers focus on. It's also rarely the one that causes problems. What catches people off guard is everything layered on top of it, especially in a coastal market like ours.
A realistic monthly payment in the Wilmington area includes:
Principal and interest: The base loan payment
Property taxes: Vary by county, city, and any special districts
Homeowners insurance: Standard coverage, separate from flood and wind
Flood insurance: Required by most lenders in federally designated flood zones
Wind or hurricane coverage: Often a separate policy or deductible in coastal NC
HOA dues: Monthly or quarterly depending on the community
Special assessments: Less predictable, but real in some communities
Maintenance reserves: Especially relevant in coastal properties with more exposure to salt air and weather
Add Property Taxes and Insurance
One thing that surprises a lot of relocating buyers is how much property tax rates vary across communities that feel geographically close to each other. Here are approximate 2026 rates:
Location | 2026 Rate (per $100 value) | Approx. Monthly Tax on $450,000 |
|---|---|---|
Wilmington (city) | $239 | |
Unincorporated Brunswick County | $128 | |
Pender County | $277 |
Fire districts, stormwater fees, and municipal overlays can add to these base rates. A home in Leland, for example, carries both the Brunswick County rate and a town rate. Always get a parcel-specific estimate, not a regional average, because the difference can be $100 or more per month on the same purchase price.
Check Flood and Wind Coverage
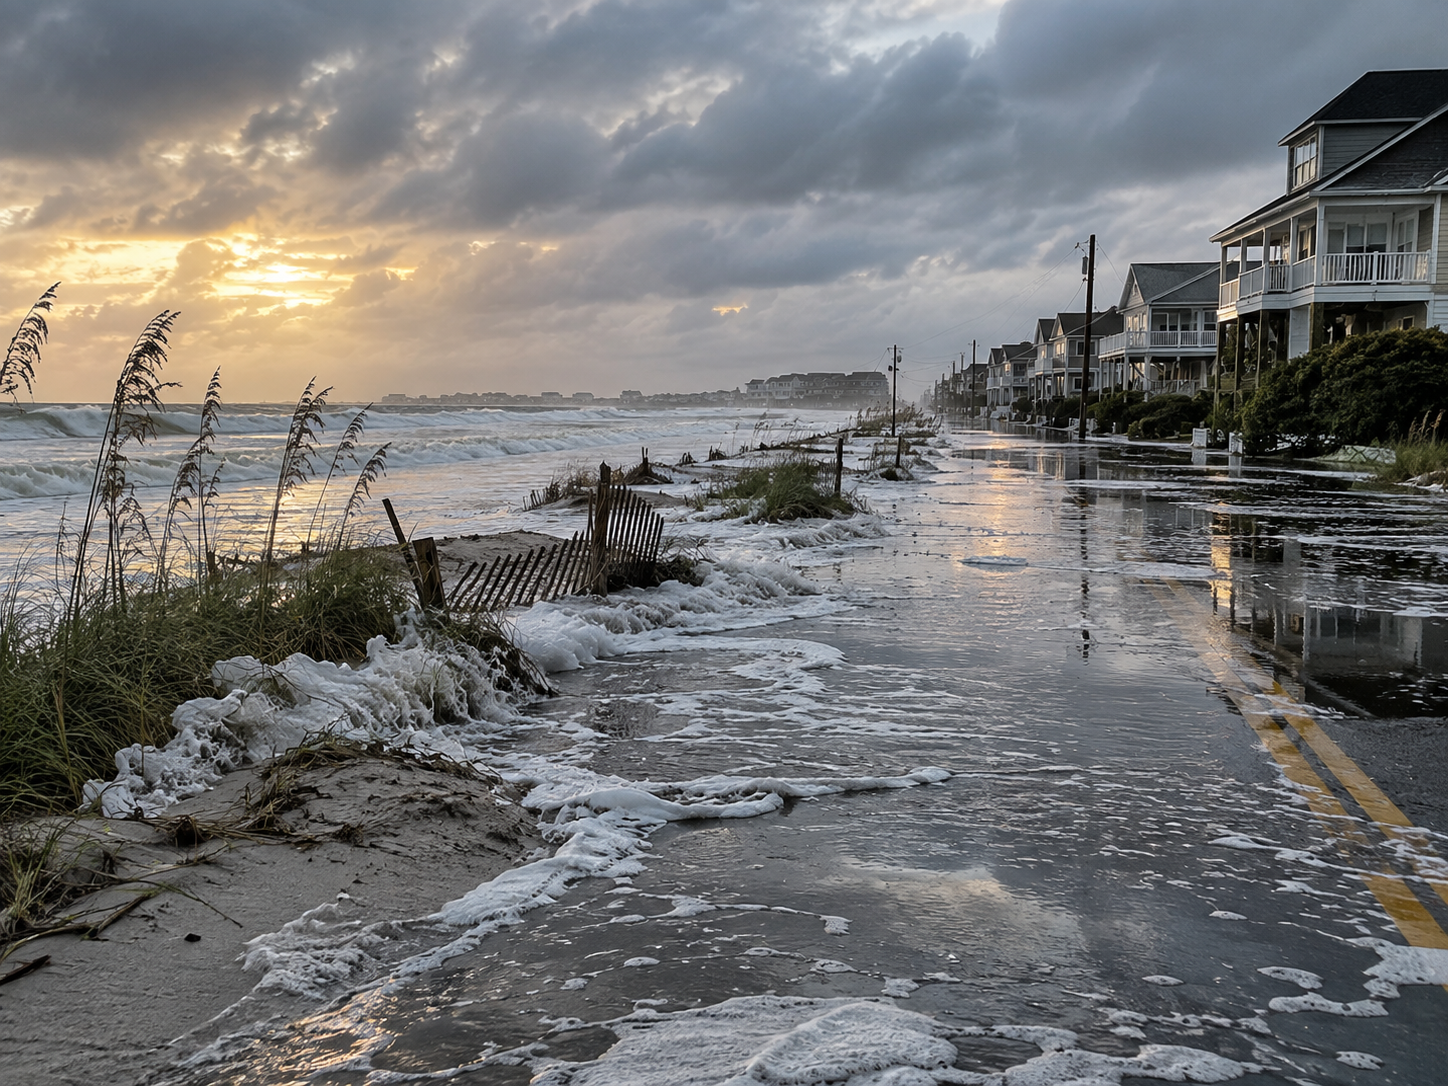
This is where coastal buyers sometimes get the biggest surprise of the whole process. Federally backed loans generally require flood insurance when a property falls in a Special Flood Hazard Area, which is common near the coast, the Cape Fear River, and inland waterways throughout New Hanover, Brunswick, and Pender Counties.
Wind coverage adds another layer. In North Carolina, wind deductibles are often written as a percentage of dwelling coverage. A 2% deductible on $300,000 of dwelling coverage means $6,000 out of pocket before the policy pays anything after a wind event. Easy to overlook until you actually need it.
One thing worth asking about, particularly with new construction in coastal communities: North Carolina's FORTIFIED program offers insurance credits for homes built to stronger wind-resistance standards. Some builders in our area are already building to FORTIFIED specs, and the savings on your annual premium can be meaningful.
Get property-specific insurance quotes before your due diligence period ends, not after.
Include HOA and Condo Costs
Communities like Brunswick Forest, St. James Plantation, RiverLights, and Landfall all carry HOA dues, and those vary widely depending on amenities, common area maintenance, and how well the reserve fund is managed. It's not just about the monthly number. It's about what the community is doing with it.
For condos, especially in beach markets like Carolina Beach, Kure Beach, or Topsail Island, the picture gets more layered. Master insurance, reserves, pending assessments, and whether the complex meets conventional lending guidelines all matter. Some condo projects in beach communities don't qualify for standard financing, which affects both your options as a buyer and your future buyer pool when you eventually sell. Ask for the HOA financials and reserve study before closing.
Protect Cash for Repairs and Maintenance
One of the most common mistakes I see, especially with first-time buyers, is putting everything into the down payment and arriving at closing with very little left. In coastal North Carolina, that's a real risk. Salt air, humidity, and storm exposure mean homes here tend to need more ongoing attention than inland properties.
Keep reserves beyond your down payment for inspections, immediate repairs, moving costs, and the deductible if something goes sideways in year one. Three to six months of housing costs in reserve after closing isn't excessive here. It's just practical.
How Does Your Timeline Affect Rate Planning?
Where you are in the process changes how you think about rate uncertainty. Someone buying in the next 60 days is in a different spot than someone who's 12 months out and still figuring out which county they want to land in.
Plan for a Purchase Within Three Months
Get a current preapproval from at least two lenders and compare them side by side, looking at rate, APR, points, origination fees, and total loan cost. Update your payment estimates before submitting offers. Rates can move between your preapproval date and an accepted contract, and you want to be working from current numbers.
Prepare for a Purchase Within Twelve Months
Use the time well. Improving your credit score, paying down revolving debt, and building up reserves can meaningfully affect both the rate you're offered and the loan options available to you. Set a flexible price ceiling and revisit it every few months as rates and inventory shift.
Build Flexibility Without a Firm Date
If you're still exploring, start with a payment limit rather than a price limit. Then compare what that payment actually buys you across different property types and locations. A waterfront home in Hampstead, a golf community in Brunswick County, a beach condo on Topsail Island, and new construction in Leland can all land in similar price territory but carry very different total monthly costs once you layer in taxes, flood insurance, and HOA dues. That's a conversation worth having before you narrow your search.
How Can Buyers Protect Their Purchasing Power?
Rate movement isn't the only lever you have, and it's worth knowing what else is on the table.
Seller-paid closing costs: Sellers can contribute toward your closing costs within loan-specific limits. For conventional loans, concessions generally range from 3% to 9% of the purchase price depending on your down payment and occupancy type.
Temporary rate buydowns: A 2-1 buydown lowers your rate by two points in year one and one point in year two before settling at the note rate. Sellers or builders often fund these as a negotiating tool.
Permanent buydowns: Paying points upfront to lower your rate for the life of the loan. Worth calculating if you plan to stay long-term.
Builder incentives: Builders in communities like Compass Pointe, Brunswick Forest, and Waterford of the Carolinas sometimes offer preferred-lender credits or rate incentives. Compare the full picture against outside lender offers. The advertised rate from a builder's preferred lender isn't always the better deal once you look at the total cost.
Larger down payment: Reduces your loan amount, lowers your payment, and may move you into a better rate tier.
These are tools for fine-tuning, not for stretching into a price range that doesn't otherwise work.
When Does Waiting to Buy Make Sense?
Honestly? Sometimes it's the right call. If the stress-tested payment at a modestly higher rate already feels uncomfortable, that's worth listening to.
Waiting tends to make sense when:
The higher-rate scenario leaves no room for savings or unexpected expenses
Reserves are thin and likely to stay that way for a while
Employment or income is in transition
The expected ownership period is short, which limits your ability to recover purchase costs
Personal readiness isn't quite there yet, and this is a lifestyle move as much as a financial one
What waiting doesn't work well for is trying to predict where rates go. Nobody gets that right consistently. And buying based on an expectation of refinancing later is a risk worth being honest about with yourself. Refinancing is an option, not a plan.
Check out this article next